
Going solo as a freelancer in Florida means you’re responsible for protecting your own business. Unlike traditional employees, you don’t have an employer’s insurance safety net.
At Providence Insurance Group, we’ve seen firsthand how the right freelancer insurance in Florida can save independent workers from financial disaster. A single liability claim or unexpected illness can derail your income and your business.
This guide walks you through the coverage types that actually matter for your freelance work.
Why Freelancers Need Real Protection
Freelancers in Florida face financial exposure that most traditional employees never encounter. When a client claims you damaged their property or provided negligent advice, you become personally liable. When illness strikes, your income stops immediately with no sick leave or disability benefits. When your camera equipment gets stolen or your laptop fails, you absorb the entire replacement cost. These situations spiral into business-ending crises without proper coverage.
The Real Cost of Liability Claims
A single lawsuit costs tens of thousands in legal fees alone, even if you win. According to data from the Small Business Administration, general liability claims average between $25,000 and $100,000 in legal and settlement costs. For service-based freelancers like consultants, designers, and marketers, professional liability claims run even higher because they involve claims of negligent advice or poor work quality.
A marketing consultant who recommends a failed strategy, a web developer whose site gets hacked, or a graphic designer whose work causes brand damage all face exposure to professional liability claims. These aren’t rare scenarios-they’re predictable business risks that need predictable insurance solutions. Professional liability coverage directly addresses this gap and costs far less than a single claim.
Income Loss When You Can’t Work
Disability strikes working-age Americans more often than most people realize. The Council for Disability Awareness reports that the average disability lasts 34.6 weeks, and back injuries, musculoskeletal disorders, and mental health conditions rank as the top causes. For a freelancer earning $5,000 monthly, a seven-week disability without coverage means $35,000 in lost income with no replacement.
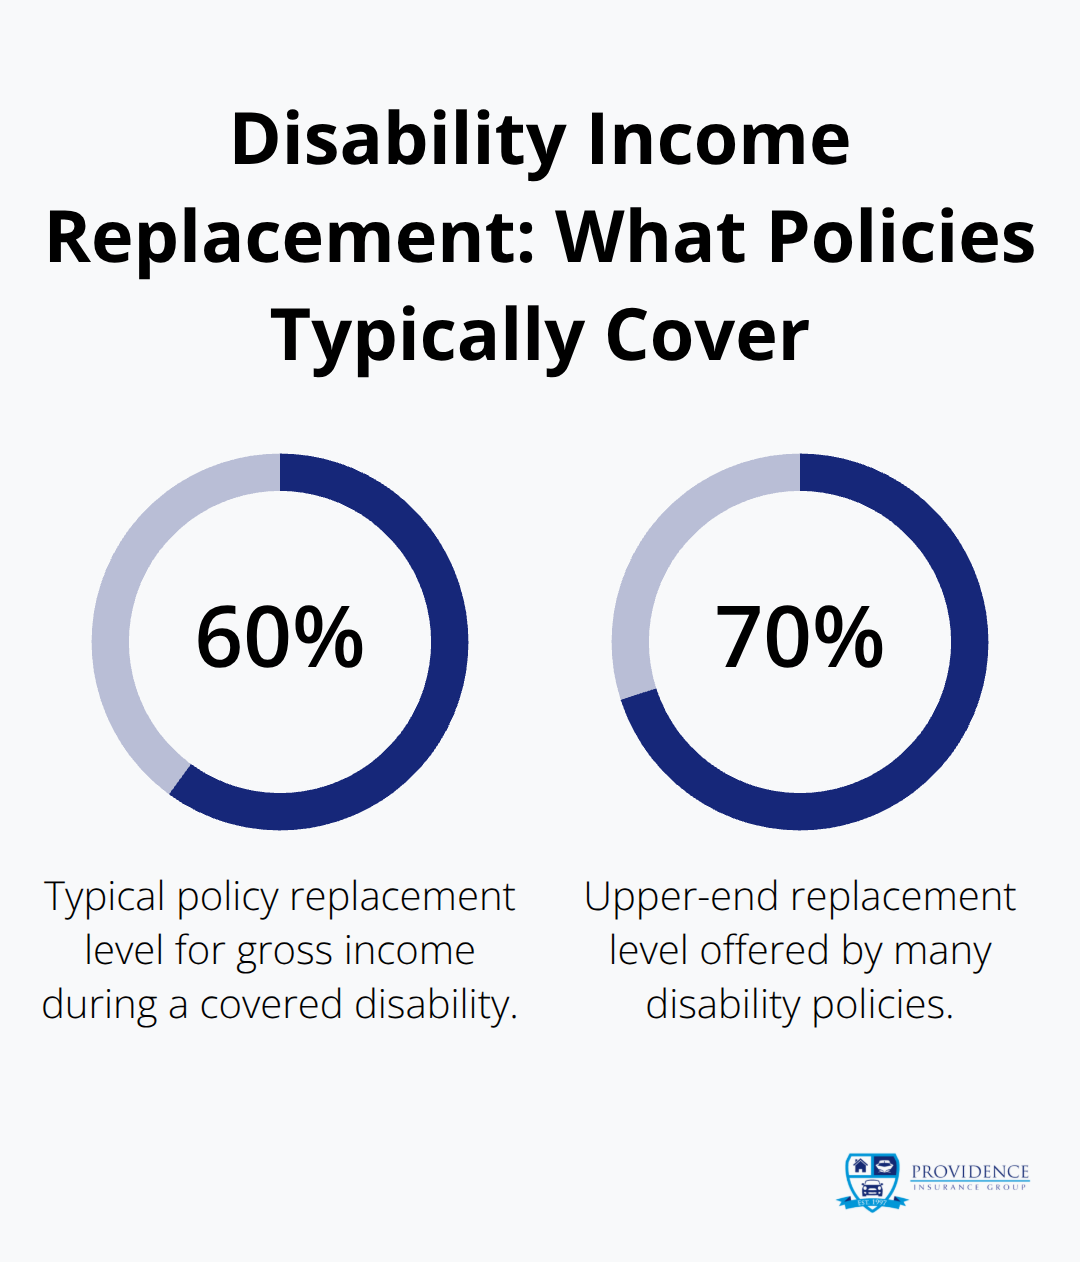
Disability insurance replaces a percentage of your income during periods when injury or illness prevents you from working. Most policies cover 60 to 70 percent of your gross income, which is realistic for maintaining your essential expenses while you recover. This coverage exists specifically because freelancers have no employer safety net.
Equipment and Property Exposure
Your business tools represent significant capital investment. A freelance photographer carries $15,000 in camera equipment. A contractor keeps $20,000 in tools on job sites. A virtual assistant relies on computers worth several thousand dollars. Business property insurance covers theft, damage, and loss of these assets.
This coverage isn’t optional for freelancers who depend on specific equipment to deliver work. Unlike homeowners insurance, which excludes business property, commercial property coverage protects your working assets at their full replacement value. Understanding what types of coverage address your specific equipment needs sets the foundation for selecting the right policies-which is exactly what we’ll explore in the next section.
Coverage Types That Actually Protect Your Florida Business
General Liability: Your First Line of Defense
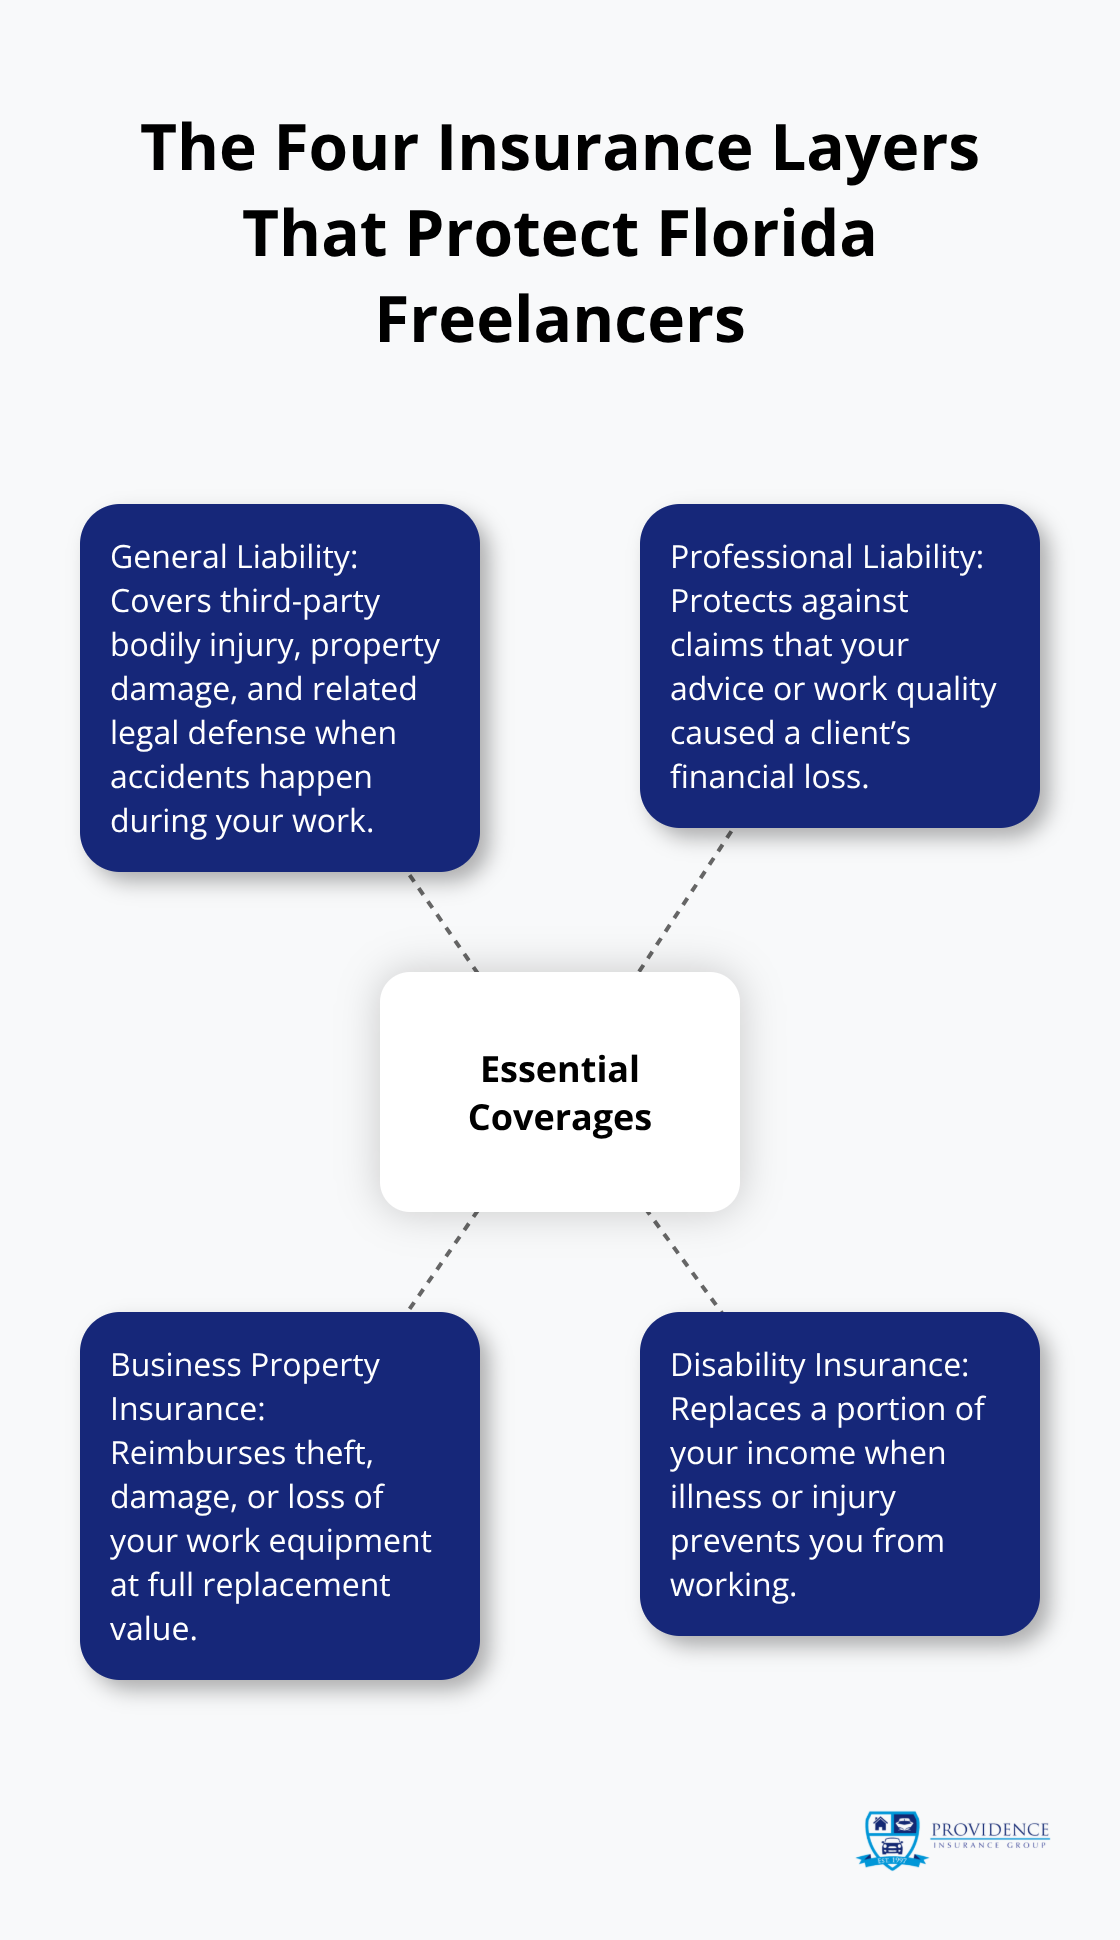
General liability insurance handles the most common threat to freelancers: someone gets hurt or property gets damaged because of your work. If a client trips over your equipment at their office or you accidentally damage their property during a project, general liability covers their medical bills and property repair costs, plus your legal defense. On average, small business owners pay around $42 per month for general liability insurance, making this an affordable protection layer you can buy. Florida freelancers in contracting, food services, landscaping, and cleaning face particularly high exposure here, which is why this coverage matters regardless of your industry.
Professional Liability: Protecting Against Claims of Negligent Work
Professional liability insurance addresses a completely different risk that general liability ignores: claims that your work or advice caused someone financial loss. A marketing consultant whose strategy tanks a client’s campaign, a web developer whose site gets hacked, or a bookkeeper whose error costs a business thousands all face professional liability exposure. This coverage protects service-based freelancers specifically and costs roughly $50 to $100 monthly depending on your profession and revenue. The difference between general and professional liability is critical because they cover entirely separate scenarios, and many Florida freelancers need both.
Business Property Insurance: Protecting Your Working Assets
Business property insurance protects the equipment and tools you depend on to produce income, covering theft, damage, fire, and weather-related losses. A contractor with $20,000 in tools, a photographer with $15,000 in camera gear, or a virtual assistant with computers and servers all have real replacement costs if something happens. This coverage reimburses you at full replacement value rather than depreciated value, which matters significantly when technology fails or gets stolen.
Disability Insurance: Replacing Income When You Can’t Work
Disability insurance addresses the income gap when illness or injury prevents you from working, and the Council for Disability Awareness reports that the average disability lasts 34.6 weeks. Most policies replace 60 to 70 percent of your gross income, meaning a freelancer earning $5,000 monthly receives roughly $3,000 to $3,500 while recovering. Back injuries, musculoskeletal disorders, and mental health conditions rank as the top causes of disability, affecting working-age Americans far more frequently than people expect.
Selecting the Right Combination for Your Work
These four coverage types work together to address your actual business vulnerabilities, not theoretical risks. Your specific freelance work determines which combination protects you most effectively. The next section walks you through how to compare quotes and find the most cost-effective options without sacrificing the protection your business actually needs.
How to Find Affordable Freelancer Insurance Without Sacrificing Protection
Request Quotes from Multiple Carriers
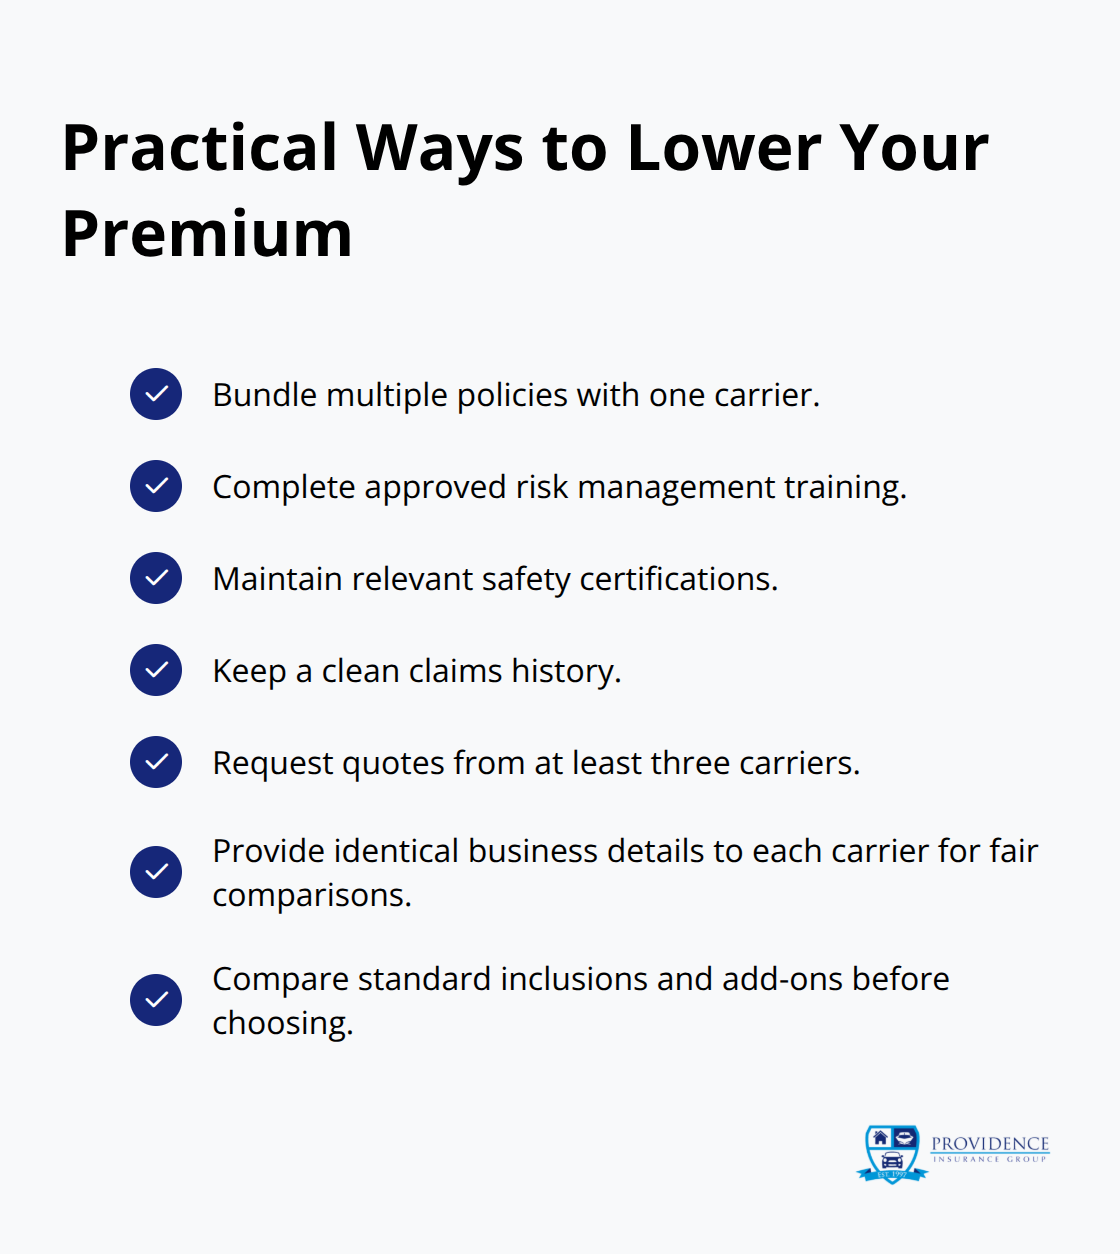
Getting multiple quotes is the only way to find freelancer insurance that actually fits your budget and business needs. When you request quotes from different carriers, you’ll discover that prices vary dramatically for identical coverage. One insurer might charge $35 monthly for general liability while another charges $60 for the same limits. Over a year, that $25 difference compounds to $300-money you could spend elsewhere in your business. Request quotes from at least three carriers before deciding, and provide each one with identical information about your business so the comparisons are actually meaningful. Many insurers offer online quote tools that take less than ten minutes, which means you can gather pricing information without lengthy phone calls or sales conversations.
Compare Coverage Details, Not Just Price
Beyond comparing raw premiums, examine what each carrier includes in their standard policies and what costs extra. Some insurers bundle professional liability with general liability at a single price, while others charge them separately. One carrier might include business property coverage in their package while another treats it as an add-on. These structural differences affect your total cost significantly. Ask each carrier about available discounts specific to your situation. Many insurers offer discounts for taking multiple policies together-bundling coverage can reduce your overall premium. Some carriers provide discounts for completing risk management training, maintaining safety certifications, or having no prior claims.
Evaluate Coverage Limits Against Your Actual Exposure
Once you understand your actual coverage needs based on your specific freelance work, you can evaluate whether the cheapest quote truly protects your business or whether a slightly higher-priced policy with better coverage limits serves you better. A contractor with $20,000 in equipment needs different property coverage limits than a virtual assistant with $5,000 in computers. A marketing consultant whose advice influences six-figure client decisions needs higher professional liability limits than a freelance writer. Match your coverage limits to your real business exposure, not to what sounds affordable in isolation.
Work with an Independent Agent for Personalized Guidance
An independent agent can access multiple carriers at once, explain what each policy actually covers, and help you identify which combination of coverage and pricing matches your real business exposure rather than pushing you toward whatever generates the highest commission. At Providence Insurance Group, we take the time to get to know your specific freelance work, which helps us customize coverage to your actual needs. We compare rates, coverages, and payment options side by side across Florida’s top insurance carriers and maximize your available discounts. This personalized approach means you avoid overpaying for coverage you don’t need while ensuring you have adequate protection for the risks your freelance business actually faces.
Final Thoughts
Protecting your freelance business in Florida requires four essential coverage types working together. General liability handles the everyday risks of client interactions and property damage, professional liability protects you when your advice or work quality gets questioned, business property insurance covers your equipment and tools at full replacement value, and disability insurance replaces your income when illness or injury stops you from working. These four layers address the real vulnerabilities that independent workers face, and they cost far less than most freelancers expect-typically $100 to $200 monthly for solid coverage.
The cost of freelancer insurance Florida varies based on your specific work, but that investment pales compared to the financial devastation a single liability claim or extended disability creates. Match your coverage to your actual business exposure rather than buying whatever sounds cheapest or most comprehensive. An independent agent accesses multiple Florida insurers at once and shows you side-by-side pricing and coverage options, identifies discounts you might miss on your own, and explains what each policy actually covers in plain language.
Contact an independent agent and provide details about your freelance work, your equipment, your typical client interactions, and your income level. Request quotes from at least three carriers so you can compare pricing and coverage side by side, ask about available discounts and bundling options that reduce your total premium, then select the combination that protects your business without overpaying. Visit Providence Insurance Group to get started with personalized guidance on freelancer insurance that actually fits your Florida business.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation