
Doral contractor liability claims can drain your business finances and damage your reputation. One incident-whether it’s a property damage claim or a worker injury-can expose you to thousands in legal fees and settlements.
We at Providence Insurance Group know that contractors need more than just basic coverage. The right insurance strategy, combined with smart risk management, protects your team and your bottom line.
What Liability Risks Actually Cost Doral Contractors
Property Damage and Bodily Injury Exposures
Contractors in Doral face three primary liability exposures that can devastate finances if left unaddressed. Property damage claims occur when your team damages a client’s building, equipment, or surrounding structures during work. Bodily injury claims arise from worker accidents on job sites, even when proper safety measures exist. Third-party claims happen when someone not employed by you suffers an injury or loss because of your work.
Florida construction data shows that the average general liability claim costs contractors between $15,000 and $50,000 in legal defense alone, before any settlement or judgment. Doral’s building boom means more projects, more exposure, and higher stakes for contractors who lack proper coverage limits.
Florida’s Mandatory Workers’ Compensation Requirements
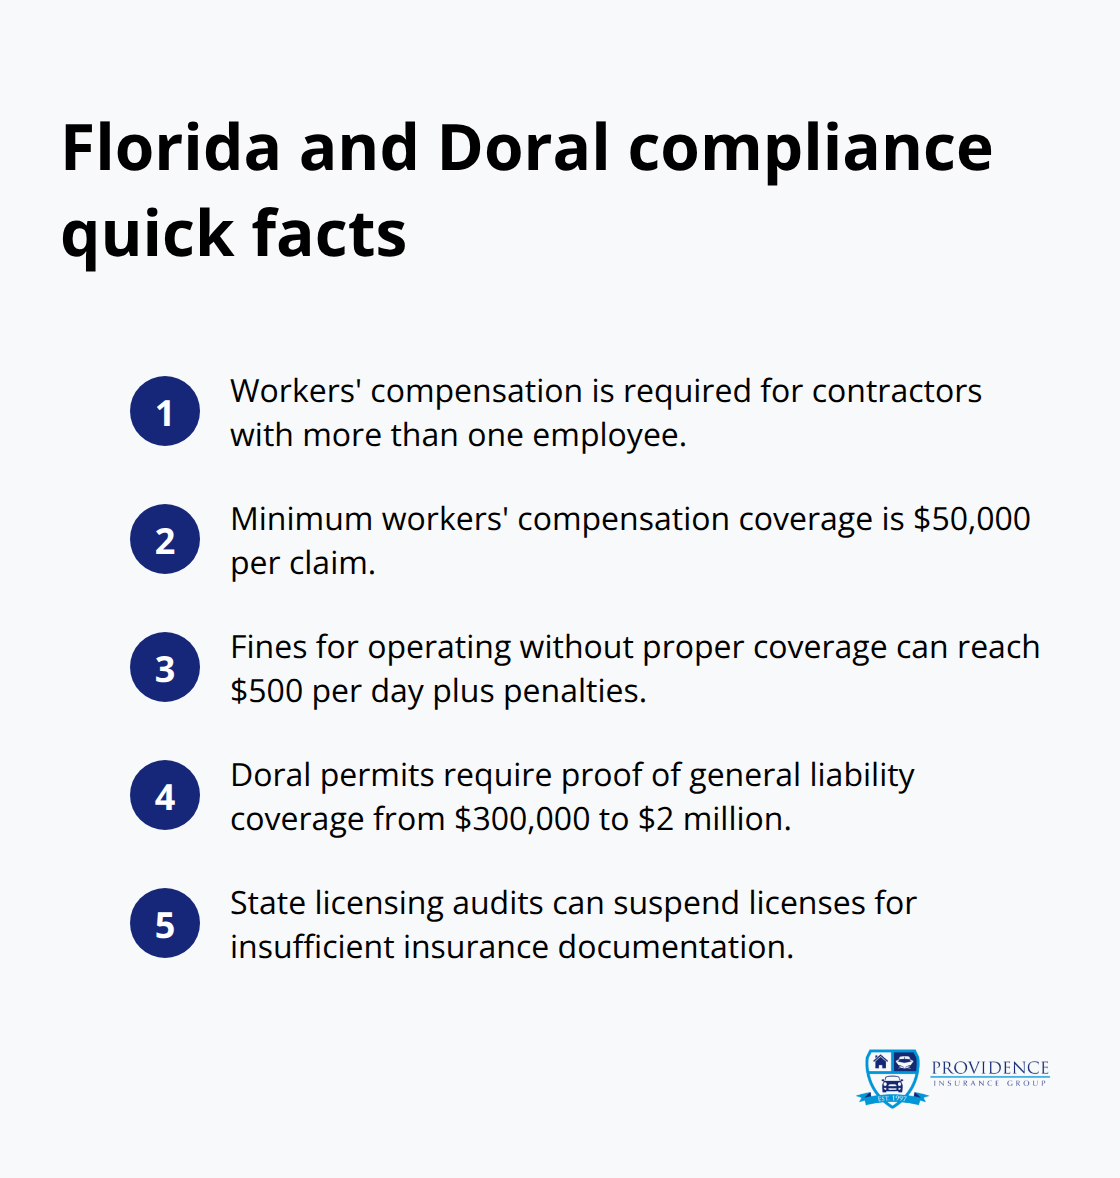
Regulatory requirements in Florida create additional pressure that many contractors underestimate. Florida Statute 440.10 mandates workers’ compensation insurance for any contractor with more than one employee, with minimum coverage of $50,000 per claim. Doral enforces these requirements strictly, and operating without proper coverage results in fines up to $500 per day plus criminal penalties.
Permit and Licensing Compliance in Doral
Doral construction permits require proof of general liability coverage before project approval, typically ranging from $300,000 to $2 million depending on project scope. The Florida Department of Business and Professional Regulation audits contractor licensing annually, and insufficient insurance documentation can result in license suspension.
Subcontractor Liability and Vicarious Exposure
Subcontractors add another layer of complexity because you remain liable for their actions on your job sites, even when they carry their own insurance. This vicarious liability means a single subcontractor mistake can trigger claims against your business. These overlapping requirements demand a coverage structure that protects against real-world exposures rather than leaving gaps that regulators or claimants will exploit-which is exactly why understanding your essential coverage options matters.
Building the Right Coverage Mix for Doral Contractors
General Liability: Your Foundation Layer
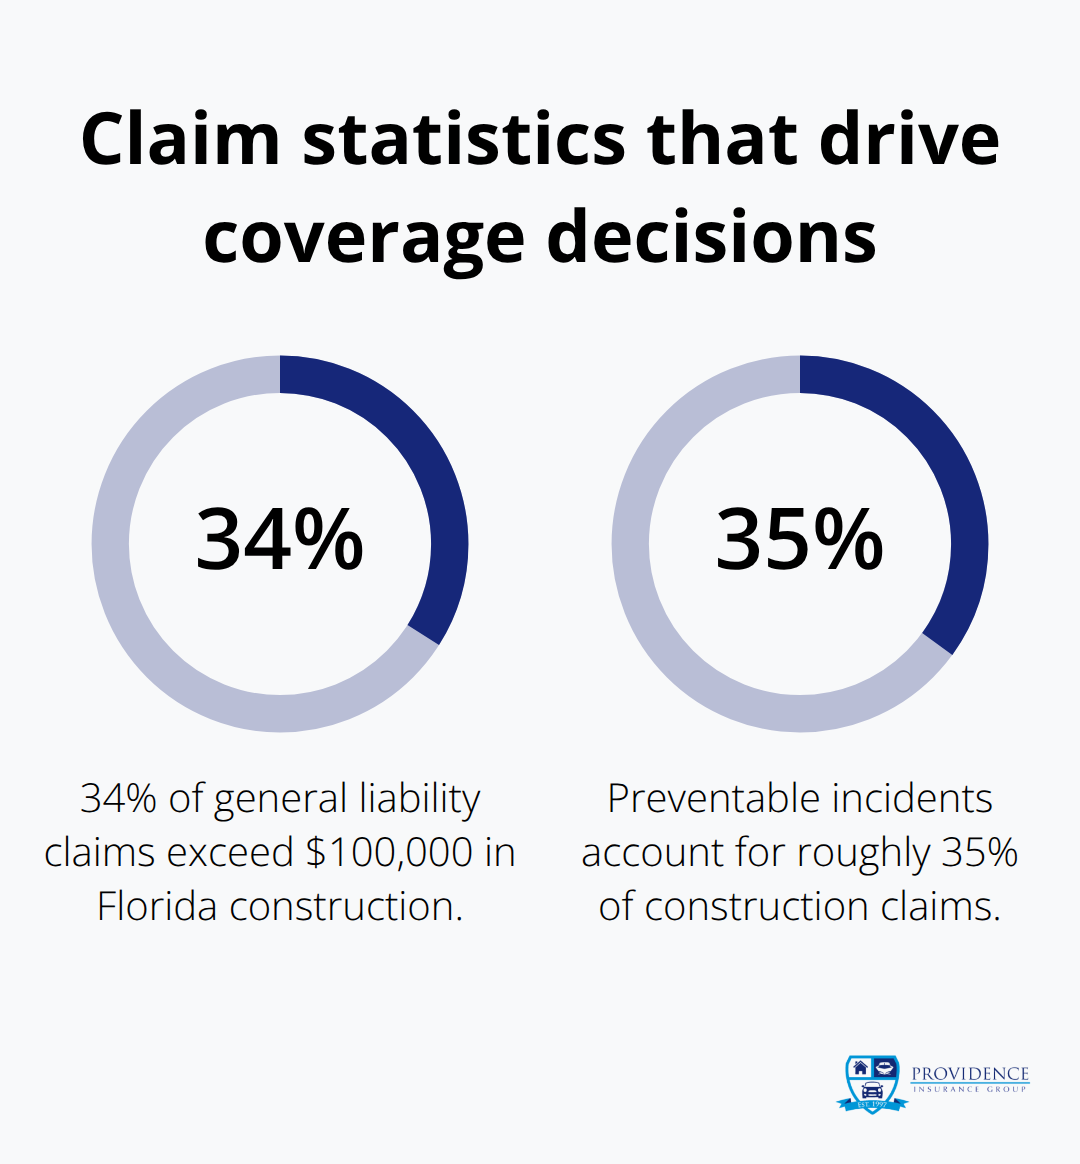
General liability insurance forms the foundation of contractor protection in Doral, but most contractors carry limits that fall short of real-world exposure. Florida construction claims data shows that 34% of general liability claims exceed $100,000, yet many contractors maintain only $300,000 in total coverage across all liability exposures. This creates a dangerous gap.
Your general liability policy should cover bodily injury, property damage, and personal injury claims that arise from your operations. For Doral contractors, minimum coverage should start at $1 million per occurrence and $2 million aggregate, particularly if you work on residential or commercial properties where damage costs run high.
Deductible Strategy Matters More Than You Think
Beyond the policy limits themselves, your deductible choice affects both your finances and your claims response. A $1,000 deductible versus a $5,000 deductible might save you $200 annually on premiums, but that math collapses the moment you face a claim. Most contractors in Doral benefit from keeping deductibles at $2,500 or lower to avoid cash flow disruption when claims arise.
Workers’ Compensation: Non-Negotiable in Florida
Workers’ compensation in Florida operates differently than many contractors expect. You cannot opt out regardless of your business structure, and Florida’s Second Injury Fund adds complexity that makes underestimating your exposure dangerous. The average workers’ compensation claim in Florida construction costs $35,000 to $75,000 per injury, according to the National Council on Compensation Insurance.
Your premium rates depend on your payroll, job classification, and claims history, but Doral contractors consistently underestimate how quickly rates climb after a single serious injury.
Umbrella and Excess Liability: Protection Against Catastrophic Claims
Umbrella and excess liability policies serve a specific purpose that many contractors misunderstand. An umbrella policy sits above your general liability and workers’ compensation, activating only when those underlying policies reach their limits. A $1 million umbrella typically costs $300 to $600 annually for contractors and provides critical protection against catastrophic claims.
The alternative-self-insuring above your base coverage limits-exposes your personal assets and business equity to seizure in litigation. Doral’s regulatory environment and the volume of construction activity mean that umbrella coverage isn’t optional for contractors who manage multiple projects simultaneously. Once you understand your coverage structure, the next step involves the operational practices that actually prevent claims from happening in the first place.
Risk Management Strategies to Reduce Claims
Safety Protocols Stop Claims Before They Start
Safety training and documentation prevent claims before they start, yet most Doral contractors treat these as checkbox exercises rather than operational priorities. The National Safety Council reports that construction workers face injury rates five times higher than workers in other industries, and preventable incidents account for roughly 35% of all construction claims. This means your safety protocols directly impact your insurance costs and your ability to retain clients.
Establish written safety procedures specific to your job types and conduct documented safety meetings before every project starts. Require all workers to sign acknowledgment forms and track near-misses and minor incidents in a centralized log-these reveal patterns that signal where serious injuries will occur next. Doral’s building inspectors increasingly ask to review your safety documentation during permit inspections, so organized records protect your reputation with city officials and demonstrate competence to potential clients.
Contract Management and Documentation
Contracts matter just as much as safety training because vague agreements create disputes that transform into claims. Your contracts should specify who carries liability for different types of work, define scope boundaries clearly, and require clients to acknowledge existing conditions before work starts. Many Doral contractors lose claims because their contracts fail to address property damage that existed before they arrived on site or injuries caused by client negligence.
Include language requiring clients to maintain their own insurance and name your company as additionally insured on their policies when appropriate. Document every change order in writing with signatures from both parties, because verbal agreements about scope changes become impossible to prove when disputes arise. This documentation protects you when clients later dispute what work was actually included in the original agreement.
Vendor Management and Subcontractor Vetting
Subcontractors represent your biggest controllable risk because their mistakes trigger claims against your license and your insurance. Before hiring any subcontractor, obtain their insurance certificates and verify coverage limits match your requirements-minimum $1 million general liability for most trades. Call their insurance carriers directly to confirm policies remain active, because expired certificates circulate constantly in the industry.
Require subcontractors to sign detailed safety agreements acknowledging your job site rules and conduct brief safety orientations before they start work. Many Doral contractors skip this step to save time, then face claims when subcontractors violate local building codes or injure themselves through negligence. Inspect their work regularly and photograph completed sections to establish quality standards, because defective work by subcontractors can create liability claims months after the job ends.
Final Thoughts
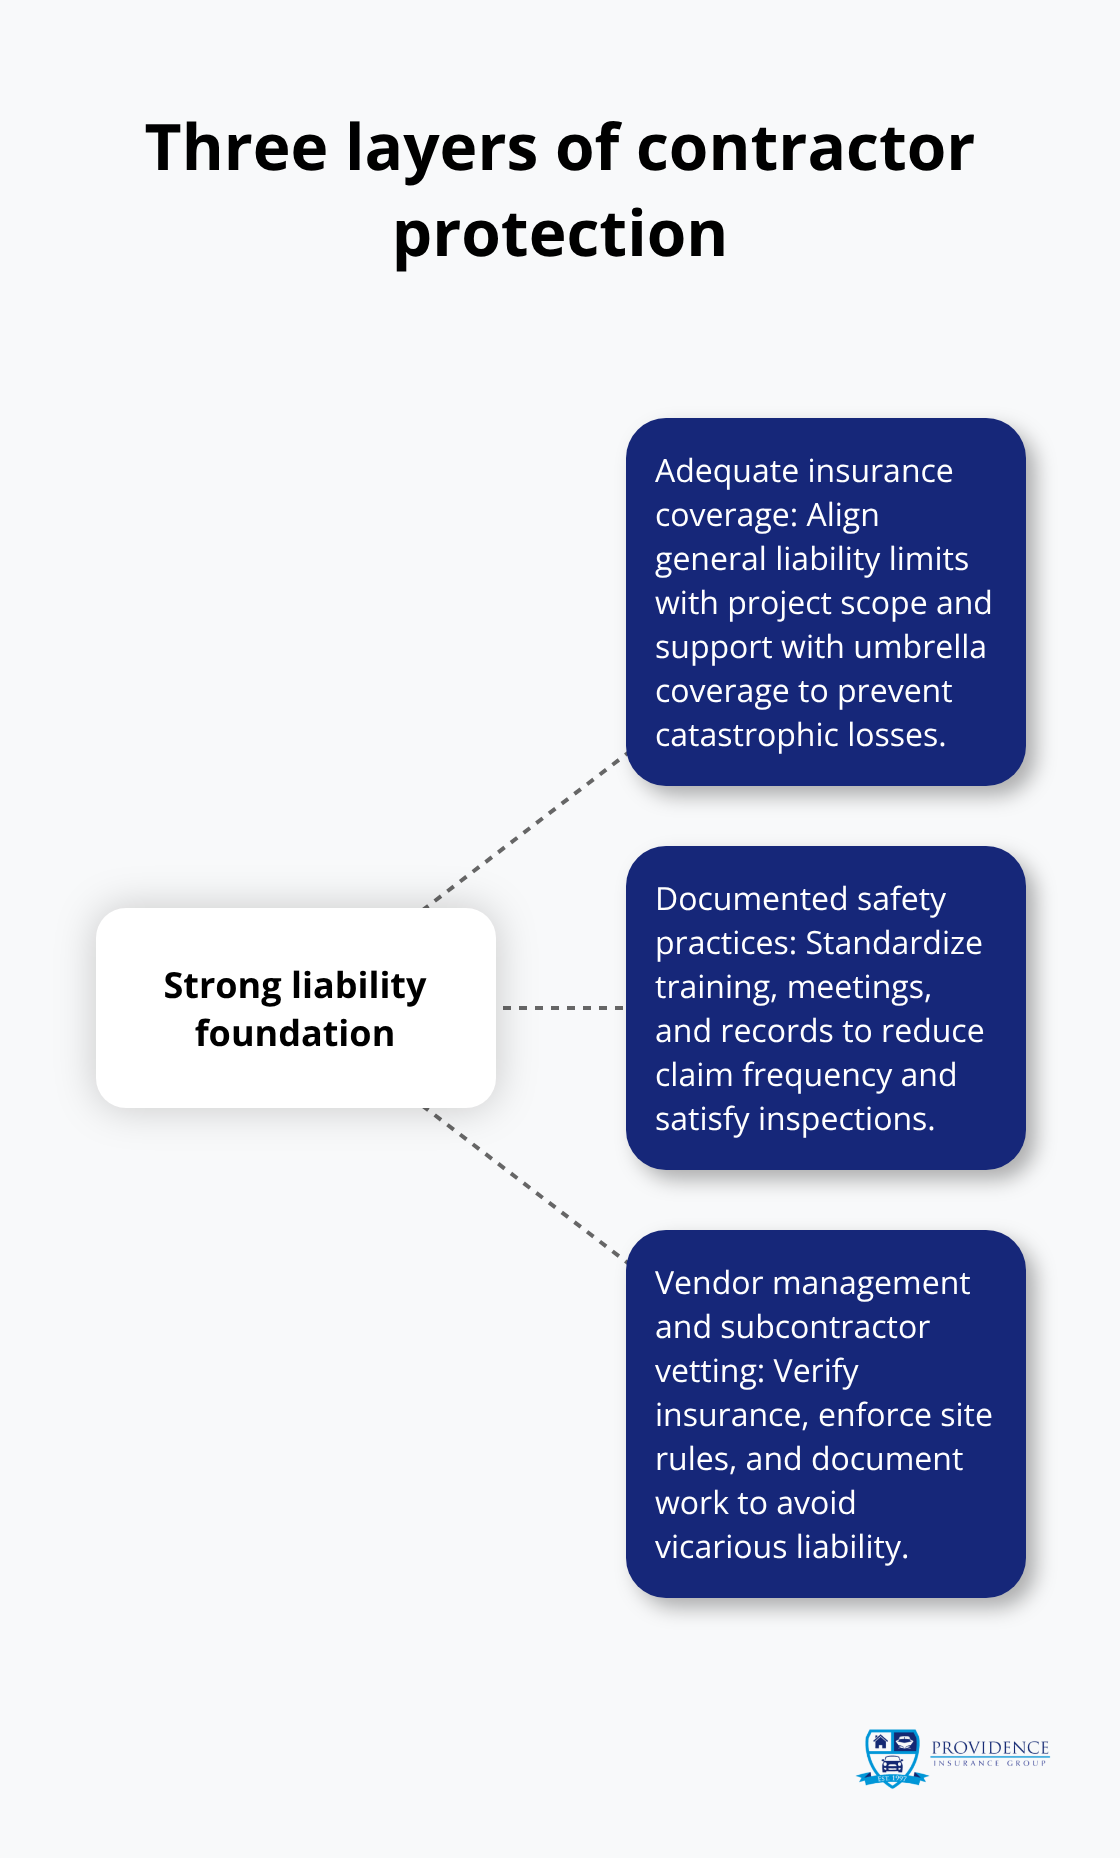
Building a strong legal foundation for your Doral contractor liability protection requires three interconnected layers: adequate insurance coverage, documented safety practices, and careful vendor management. Your general liability and workers’ compensation policies form the baseline protection, while umbrella coverage prevents catastrophic claims from destroying your business equity. Safety protocols and contract documentation reduce claims before they happen, and subcontractor vetting eliminates the single biggest source of preventable liability exposure.
We at Providence Insurance Group understand that contractors need more than just policy documents-we take the time to understand your specific operations, the types of projects you manage, and the real exposures your team faces daily. As an independent agency, we work with many of Florida’s top insurance carriers and compare rates, coverages, and payment options side by side to maximize your discounts and customize protection for your actual needs. Contact us to review your current coverage and identify gaps before a claim exposes them.
We’ll assess whether your general liability limits match your project scope, verify your workers’ compensation classification is accurate, and determine whether umbrella coverage makes financial sense for your operation. Visit our website or call us directly to schedule a consultation. Your legal foundation depends on getting this right now, not after a claim forces the conversation.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation